Closing Costs in London, Ontario: What Buyers Need to Know in 2026
When you're budgeting to buy a home in London, Ontario, your down payment is only part of the picture. Closing costs in London, Ontario include Ontario's Land Transfer Tax, legal fees, a home inspection, title insurance, and a handful of smaller adjustments — and nearly all of them are due on closing day, not spread across your mortgage. As a London REALTOR® with Century 21, First Canadian, I walk every buyer through a closing cost estimate before they write an offer, because the week before closing is the worst time to discover what you actually owe. Here's what goes into that number, using Ontario's official tax formula and current market figures.
Key Takeaways
- Ontario's Land Transfer Tax (LTT) is calculated on a sliding scale from 0.5% to 2.0% of your purchase price, per Ontario's Ministry of Finance.
- First-time buyers can claim a rebate of up to $4,000 against their LTT — using Ontario's own formula, that erases the tax entirely on homes priced up to roughly $368,000.
- Unlike Toronto, the City of London does not charge a separate municipal land transfer tax — London buyers pay the provincial LTT only.
- If your down payment is under 20%, expect a mortgage default insurance premium of 0.6% to 4.0% of your loan amount, per CMHC's published rate table.
- Legal fees, a home inspection, and title insurance are separate costs — ask your lawyer and inspector for written quotes before you remove conditions.
How Ontario's Land Transfer Tax Works for London Buyers
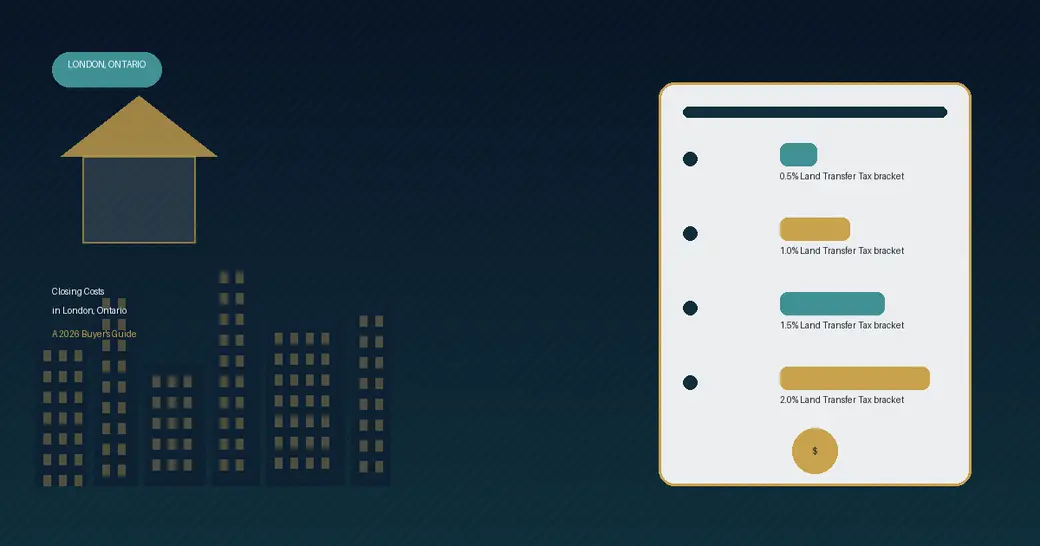
Ontario's Land Transfer Tax is the single biggest closing cost for most London buyers, and it's calculated on a sliding scale rather than a flat percentage. According to Ontario's Ministry of Finance, the current rates are: 0.5% on the portion of the purchase price up to $55,000; 1.0% on the portion from $55,000 to $250,000; 1.5% on the portion from $250,000 to $400,000; and 2.0% on the portion above $400,000 (a higher 2.5% rate applies only to the portion above $2,000,000 for land with one or two single-family residences, which covers very few London purchases).
To put that in real terms: on a $590,550 home — the average sale price across the London and St. Thomas market in August 2026, per the Canadian Real Estate Association's board statistics — the Land Transfer Tax works out to roughly $8,286. That's a real number buyers need in their closing budget, separate from their down payment and mortgage.
The First-Time Buyer Land Transfer Tax Rebate
If this is your first home, Ontario's Ministry of Finance allows a rebate of up to $4,000 against your Land Transfer Tax. Working through Ontario's own calculation, that rebate wipes out the LTT entirely on homes priced up to approximately $368,000 and reduces the tax owing on anything above that.
To qualify, you must be at least 18, a Canadian citizen or permanent resident (or become one within 18 months of registering the property), and you — along with your spouse, if you have one — must never have owned a home or an interest in one, anywhere in the world. You also need to move into the home as your principal residence within nine months of closing. In my experience helping first-time buyers across London and Middlesex County, this rebate is one of the most under-discussed parts of a purchase budget — I build it into every first-time buyer's closing cost estimate from the start, because it genuinely changes what a buyer needs in the bank on closing day.
Why London Doesn't Have a Municipal Land Transfer Tax — Unlike Toronto
Buyers relocating to London from the Greater Toronto Area often ask me whether they'll owe a second, municipal land transfer tax on top of the provincial one. They won't. Ontario's Land Transfer Tax rules apply province-wide, and Toronto is the only municipality in Ontario that layers an additional municipal land transfer tax on top of the provincial rate. London buyers pay the provincial LTT only — which, on an average-priced home, can mean thousands of dollars less in closing costs than an equivalent purchase inside Toronto's city limits.
Mortgage Default Insurance and Your Closing Costs
If your down payment is less than 20% of the purchase price, your lender will require mortgage default insurance, most commonly through the Canada Mortgage and Housing Corporation (CMHC). This isn't typically a cash cost due at closing — the premium is usually added to your mortgage principal — but it does affect your monthly payment, so it belongs in any honest closing cost conversation.
Per CMHC's published premium table, the premium is charged as a percentage of your total loan amount and rises as your loan-to-value ratio increases: 0.60% at up to 65% loan-to-value, climbing through the mid-range brackets to 4.00% at 90.01% to 95% loan-to-value (the maximum CMHC insures for most owner-occupied purchases). A buyer putting down close to 20% will pay a meaningfully smaller premium than one putting down the minimum, which is worth factoring into how much down payment makes sense for your situation.
Other Closing Costs Buyers in London Should Budget For
Beyond Land Transfer Tax and mortgage insurance, a few other costs show up on nearly every closing statement I review with clients:
Legal fees. Ontario law requires a real estate lawyer to close your purchase. Fees vary by law firm and file complexity, so ask for a written quote early — don't assume your lawyer's fee is bundled into any other number.
Home inspection. Not legally required, but strongly recommended on resale homes. Your inspector sets their own fee; get it in writing before your conditional period starts.
Title insurance. Most lenders require a title insurance policy, arranged through your lawyer, protecting against issues like survey discrepancies or undisclosed liens.
Tax and utility adjustments. On closing day, you reimburse the seller for any property taxes or utilities they've prepaid beyond the closing date — a routine line item your lawyer calculates and includes in your statement of adjustments.
HST. Resale homes in Ontario are generally exempt from HST. If you're buying new construction, HST does apply — ask your builder how it's handled in your purchase price before you sign.
A Local Example: Closing Costs on an Average London Home in 2026
Here's how it comes together for a first-time buyer purchasing the August 2026 LSTAR-area average home at $590,550: Land Transfer Tax of roughly $8,286, reduced by the $4,000 first-time buyer rebate, leaves about $4,286 owing to the province. Add legal fees, a home inspection, title insurance, and tax adjustments — each quoted individually by your lawyer and inspector — and a first-time buyer's true closing cost total, outside the down payment itself, typically lands in the thousands rather than the tens of thousands. A repeat buyer without the rebate should budget for the full $8,286 in Land Transfer Tax alone. Every file is different, which is exactly why I walk clients through their own numbers rather than a generic average.
Frequently Asked Questions About Closing Costs in London, Ontario
Q: How much are closing costs when buying a home in London, Ontario?
Land Transfer Tax is the largest single cost and is calculated on Ontario's sliding scale — about $8,286 on an average-priced London home in August 2026. Add legal fees, a home inspection, and title insurance, each quoted separately by your professionals, for your full total.
Q: Do first-time buyers pay Land Transfer Tax in London, Ontario?
Often little or none. Ontario's first-time buyer rebate covers up to $4,000 of the tax, which eliminates it entirely on homes priced up to roughly $368,000 based on the current rate structure.
Q: Is there a municipal land transfer tax in London, Ontario, like in Toronto?
No. Toronto is the only Ontario municipality with its own land transfer tax layered on top of the provincial one. London buyers pay the provincial Land Transfer Tax only.
Q: When are closing costs due?
The vast majority of closing costs — Land Transfer Tax, legal fees, title insurance, and tax adjustments — are due on your closing date, paid through your lawyer's trust account alongside your down payment funds.
Q: Can closing costs be negotiated with the seller?
Closing costs like Land Transfer Tax and legal fees are paid to the government and your professionals, not the seller, so they aren't negotiable in the way price is. What can sometimes be negotiated is which party covers certain adjustments or minor repair credits — your REALTOR® can advise on what's realistic for your specific offer.
Ready to Budget for Your London, Ontario Home Purchase?
Closing costs catch a lot of buyers off guard simply because no one walks them through the real numbers before they're staring at a lawyer's statement of adjustments. Whether you're a first-time buyer wondering if the rebate applies to you, or you're moving within Middlesex County and want a realistic total before you start house hunting, I'd rather you ask the question now than find out the hard way at closing. Call me at (647) 883-7135 or visit 519propertyfinder.com to set up a free consultation, and I'll walk you through what your specific purchase will actually cost from offer to keys.
Categories
- All Blogs (78)
- Compare Neighbourhoods (3)
- Downsizing & Upsizing (2)
- First-Time Home Buyers (6)
- Home Selling Tips (1)
- Investment Properties (2)
- London Ontario Real Estate (5)
- Market Updates (11)
- Middlesex (15)
- Neighbourhood Guides (15)
- New Construction (5)
- Oxford County Real Estate (11)
- Property Taxes & Closing Costs (3)
- Relocation Guides (2)
- Rural & Small Town Living (9)
- Schools & Family Neighbourhoods (6)
- Seasonal (3)
Recent Posts