Bank of Canada Rate Hike: What It Means for London, Ontario
On October 28, 2026, the Bank of Canada delivered a rate hike — raising its target for the overnight rate by 25 basis points, to 2.50%, its first increase in three years. If you're buying, selling, or carrying a mortgage anywhere in London, Middlesex County, or Oxford County right now, that single decision touches your numbers whether you've noticed it yet or not. I'm Gloria Roman, a REALTOR® with Century 21, First Canadian, and clients have been asking me all week what this actually means for them. Here's the straight answer, grounded in what the Bank of Canada and the lenders themselves have published — not guesswork.
Key Takeaways
- The Bank of Canada raised its policy rate 25 basis points to 2.50% on October 28, 2026, citing inflation running higher and lasting longer than forecast, driven mainly by high energy prices.
- The Bank Rate is now 2.75% and the deposit rate 2.45%; the Bank says it will "proceed carefully" but hasn't ruled out another increase.
- Major lenders moved immediately: National Bank of Canada raised its prime rate 25 basis points to 4.70%, effective October 29, 2026, with other prime-rate-linked lenders following the same pattern.
- The next scheduled rate announcement is December 9, 2026 — worth marking on your calendar if you're timing a purchase, a renewal, or a pre-approval.
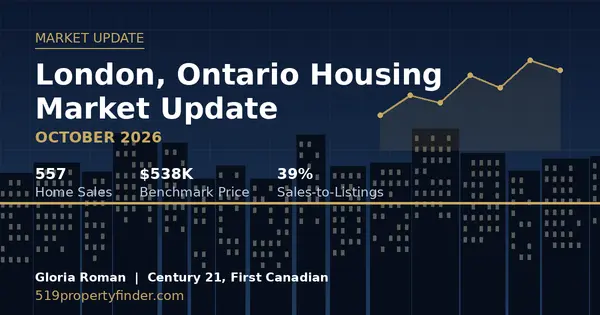
- Locally, the London and St. Thomas Association of REALTORS® recorded 557 home sales in October 2026 at an average price of $596,951, giving useful context for what this rate environment is landing on top of.
What the Bank of Canada's October Rate Hike Actually Changed
After holding steady at 2.25% through the summer and into September, the Bank of Canada's Governing Council raised the target for the overnight rate to 2.50% on October 28, 2026. In the Bank's own words, the move came because "CPI inflation has been around 3% since April" and is "expected to rise to about 3½% by the end of the year," pushed up mainly by persistent energy-price pressure rather than a broad-based spike — outside of gasoline, inflation ran at 2.2% in September, with core measures staying close to 2%.
The Bank was explicit that it isn't finished watching the situation: officials noted "there could be a need to increase the policy rate further" but that "Governing Council agreed to proceed carefully." Its own forecast has inflation averaging 3% through 2027 before easing back toward 2% by the middle of 2028. The next scheduled decision lands on December 9, 2026, and that date is now the one to watch if you're trying to time a purchase, a pre-approval, or a mortgage renewal in London or anywhere across Middlesex and Oxford counties.
Why This Matters If You Carry a Variable-Rate Mortgage in London or Middlesex County
Variable-rate mortgages and home equity lines of credit are priced off your lender's prime rate, and prime moves in near lockstep with the Bank of Canada's overnight rate. National Bank of Canada confirmed the pattern immediately, raising its own prime rate by 25 basis points to 4.70%, effective October 29, 2026 — the day after the Bank's announcement. If you're on a variable rate or carrying a HELOC on a property in London, Strathroy, Woodstock, or anywhere else in the region, you should expect your lender to have made the same move, which means either a higher payment or, on a fixed-payment variable product, more of each payment going to interest and less to principal.
If you're not sure which type of mortgage you have or how directly it tracks prime, that's a five-minute conversation with your lender or mortgage broker worth having now rather than after your next statement arrives. I'm also happy to walk through what a rate move like this does to your numbers on a specific property you're watching.
What It Means If You're Buying in London or Oxford County Right Now
A higher policy rate doesn't change the price of a home overnight, but it does change what a given monthly payment buys you, and it can shift how a lender's affordability calculation treats your application. Federally regulated lenders qualify buyers against a rate higher than their actual contract rate, so when rates move up, that qualifying bar moves too — worth confirming directly with your mortgage professional before you fall in love with a price range.
Locally, this is landing on an already-cautious market. The London and St. Thomas Association of REALTORS® recorded 557 home sales across the region in October 2026, with the City of London's average sale price at $596,951 and the composite MLS® Home Price Index benchmark at $538,000. To the west, the Woodstock Ingersoll Tillsonburg & Area Association of REALTORS® reported 154 sales in September 2026 at an average price of $636,664, with a benchmark price of $566,700. Neither board has published a read yet on how the October rate move has affected activity — that data won't exist until next month's release — but a buyer weighing a purchase in this window should go in with an up-to-date, rate-adjusted affordability number rather than one calculated even a few weeks ago.
If Your Mortgage Renewal in Middlesex or Oxford County Is Coming Up
If your mortgage is coming up for renewal over the next several months, this is the moment to start the conversation with your current lender or a mortgage broker rather than waiting for the renewal letter to arrive. Rates locked in several years ago, during a much lower-rate period, can mean a meaningful payment jump at renewal even without any further Bank of Canada moves between now and then. Getting ahead of it — comparing what your current lender will offer against the broader market, and understanding whether a fixed or variable product makes more sense for your situation — generally leaves you with more options than waiting until the last few weeks.
I don't give mortgage advice myself; that's a conversation for a licensed mortgage professional. But I can help you think through how a renewal might change your plans if you're also considering selling, downsizing, or moving within London or Middlesex County around the same time.
What to Watch for on December 9
The Bank of Canada's next scheduled rate announcement is December 9, 2026. Given the Bank's own language about "proceeding carefully" and keeping the door open to a further increase if energy-driven inflation doesn't ease, that date matters for anyone timing a purchase, a pre-approval lock, or a renewal decision between now and the end of the year. I'll be watching it closely and will share what it means for London and Middlesex County buyers and sellers as soon as the decision is public.
Frequently Asked Questions About the October 2026 Rate Hike
Did the Bank of Canada raise or lower interest rates in October 2026?
It raised rates. On October 28, 2026, the Bank of Canada increased its target for the overnight rate by 25 basis points, from 2.25% to 2.50% — its first increase in three years.
How does this affect my mortgage payment?
If you have a variable-rate mortgage or a HELOC, your lender's prime rate has likely already moved up — National Bank of Canada raised its prime to 4.70% effective October 29, 2026 — which typically means a higher payment or less of each payment going toward principal. Fixed-rate mortgages aren't affected until renewal.
When is the next Bank of Canada rate decision?
December 9, 2026. The Bank has said it could raise rates further if energy-driven inflation doesn't ease, but that it will "proceed carefully."
Should I wait to buy a home in London or Middlesex County until rates come down?
That depends entirely on your own finances, timeline, and the specific property you're considering — there's no single right answer for every buyer. I'd rather run your actual numbers with you than guess, so you can decide with real information instead of headlines.
Does this rate hike affect home prices in London, Ontario?
Not directly or immediately. The London and St. Thomas Association of REALTORS® reported 557 sales in October 2026 at an average price of $596,951, but that figure predates the October 28 rate decision — next month's release will be the first to reflect any market response.
Thinking Through Your Next Move?
A rate decision like this one can feel like it changes everything, but for most buyers, sellers, and homeowners it changes the math, not the fundamentals of a good decision. Whether you're weighing a purchase in London, watching a renewal approach in Middlesex County, or wondering what a HELOC on an Oxford County property will cost next year, I'd rather sit down with your actual numbers than let you guess from a news headline. I'm Gloria Roman, REALTOR® with Century 21, First Canadian, and I help buyers, sellers, and homeowners across London and the surrounding region make sense of moments exactly like this one.
Reach out any time at (647) 883-7135 or romanofrealestate@gmail.com, or schedule a free consultation to talk through what this rate environment means for your plans.
Categories
- All Blogs (105)
- Compare Neighbourhoods (4)
- Downsizing & Upsizing (2)
- First-Time Home Buyers (8)
- Home Selling Tips (2)
- Investment Properties (3)
- London Ontario Real Estate (20)
- Market Updates (14)
- Middlesex (21)
- Neighbourhood Guides (22)
- New Construction (6)
- Oxford County Real Estate (18)
- Property Taxes & Closing Costs (4)
- Relocation Guides (2)
- Rural & Small Town Living (15)
- Schools & Family Neighbourhoods (7)
- Seasonal (4)
Recent Posts